Long-term financial planning requires careful budgeting, responsible borrowing, and a clear understanding of future financial obligations. Whether individuals want to purchase a home, expand a business, pay for education, or manage unexpected expenses, access to dependable financing can make a meaningful difference. Reliable Loan Services help borrowers evaluate suitable financing options, understand repayment conditions, and make informed decisions that support their financial goals.
Instead of treating borrowing as a short-term solution, individuals can incorporate loans into a broader financial strategy that balances current needs with future priorities. When combined with responsible spending, effective Tax Planning, modern Financial Technology, and structured Wealth Management, reliable lending can help individuals build financial stability and prepare for important milestones.
Understanding the Role of Reliable Loan Services
Reliable Loan Services provide borrowers with structured access to financing while helping them understand interest rates, repayment schedules, eligibility requirements, and associated fees. These services can support financial planning by making borrowing costs more predictable and helping individuals determine whether a loan fits their income and long-term objectives. Transparency and responsible lending practices are particularly important when borrowers are managing multiple financial commitments.
Creating Financial Stability Through Responsible Borrowing
Responsible borrowing begins with understanding why financing is necessary and how repayment will affect future cash flow. A reliable lender explains the loan’s total cost, repayment period, interest structure, and potential penalties before an agreement is signed. This information allows borrowers to compare available options and avoid commitments that could interfere with essential expenses, emergency savings, or retirement contributions.
For example, a borrower considering a home loan should evaluate monthly payments alongside property taxes, insurance, maintenance, and other household expenses. Looking at the complete financial picture helps prevent a manageable loan from becoming a long-term burden.
Improving Access to Suitable Financing
Different financial goals require different financing arrangements. Personal loans may help cover planned expenses, mortgages support property purchases, and business loans can finance equipment or expansion. Reliable Loan Services help borrowers understand these distinctions and identify options that align with their circumstances.
Choosing the right loan structure can improve financial flexibility. Borrowers who understand their options are better positioned to select appropriate repayment periods, compare borrowing costs, and maintain sufficient cash reserves for unexpected expenses.
Supporting Long-Term Financial Goals
Financing Major Life Milestones
Purchasing a home, pursuing higher education, and starting a business are important milestones that may require substantial capital. Suitable Loan Services can make these goals more achievable by providing financing with defined repayment terms. Instead of spending all available savings on a single purchase, borrowers may retain some liquidity for emergencies and ongoing expenses.
However, preserving savings should not automatically justify taking a loan. Borrowers must compare the interest cost with the potential benefits of retaining cash. A financing decision is more sustainable when the expected benefits, repayment capacity, and alternative funding options have been carefully evaluated.
Aligning Loans With Future Income
A loan should fit both present income and reasonably anticipated future financial circumstances. Borrowers who expect changes in employment, family expenses, or business revenue should consider how these changes could affect their ability to make payments. Fixed repayment obligations can become difficult when income declines unexpectedly.
Creating financial projections before borrowing helps individuals estimate affordability over the entire repayment period. A reliable loan provider can explain available repayment structures, but borrowers should independently assess whether the proposed commitment remains manageable under less favorable financial conditions.
Managing Cash Flow and Debt Repayment
Effective cash flow management ensures that income can cover regular expenses, debt payments, savings, and other financial priorities. Reliable Loan Services can support this process by providing predictable repayment schedules and clear loan statements. When borrowers understand exactly when payments are due and how balances change, they can organize their budgets more effectively and reduce the risk of missed payments.
Building a Practical Repayment Strategy
A practical repayment strategy begins with calculating monthly income after taxes and subtracting essential living expenses. The remaining amount must cover loan payments, savings contributions, and discretionary spending. Borrowers should also consider variable expenses and maintain an emergency reserve instead of allocating every available dollar toward debt.
Understanding the difference between principal and interest is equally important. Early payments on some amortizing loans may contain a larger interest component, depending on the loan structure. Reviewing the repayment schedule helps borrowers understand how their balance changes and whether additional principal payments could reduce total interest costs.
Before making extra payments, borrowers should check for prepayment fees and consider whether paying down debt is more beneficial than maintaining essential savings.
Avoiding Excessive Debt
Taking on multiple loans without evaluating total obligations can create financial pressure. Even when individual monthly payments appear affordable, their combined cost may consume too much disposable income. Reliable Loan Services should clearly communicate repayment requirements, while borrowers should calculate their total debt obligations before accepting additional financing.
A sustainable borrowing strategy prioritizes necessary expenses, limits unnecessary credit, and avoids relying on new loans to repay existing obligations. Regularly reviewing outstanding balances and future payment dates helps borrowers identify potential difficulties early and take corrective action before financial problems become more serious.
Integrating Tax Planning Into Borrowing Decisions
Understanding Potential Tax Implications
Some jurisdictions allow eligible businesses to deduct qualifying interest expenses, while certain property-related arrangements may receive specific tax treatment. However, personal loan interest is not automatically tax-deductible, and tax benefits should never be assumed without checking applicable rules.
Borrowers should maintain accurate loan statements, payment records, and supporting documents. Consulting a qualified tax professional can help determine whether particular expenses qualify for deductions and how borrowing affects annual tax obligations.
Coordinating Loans With Annual Financial Planning
Integrating debt repayments into annual Tax Planning helps individuals estimate their available income more accurately. Business owners, for example, may need to coordinate loan payments with tax deadlines, operating costs, and periods of reduced revenue. A well-organized financial calendar can reduce the likelihood of liquidity problems.
Borrowers should evaluate the complete after-tax financial impact of a loan rather than focusing exclusively on advertised interest rates. Considering fees, tax implications, repayment obligations, and available deductions provides a more realistic foundation for long-term financial decisions.
Using Financial Technology to Make Better Decisions
Financial Technology has improved how borrowers compare financing products, monitor repayment schedules, and manage financial information. Digital lending platforms, online calculators, account dashboards, and automated payment reminders can simplify many parts of the borrowing process. When these tools are supported by appropriate security measures and transparent lending practices, they can help individuals make more informed financial decisions.
Comparing Loan Options Digitally
Online loan comparison tools allow borrowers to examine interest rates, repayment periods, estimated monthly installments, and certain fees. These tools can make initial research more efficient, especially when several lenders offer different loan structures.
However, advertised rates may not represent the final terms available to every applicant. Eligibility requirements, credit history, income, and lender-specific conditions can affect the actual offer. Borrowers should verify the annual percentage rate where applicable, review the complete agreement, and confirm the total repayment amount before making a commitment.
Improving Payment Management With Digital Tools
Digital financial platforms can help borrowers track due dates, monitor balances, and organize payment records. Automated reminders and scheduled payments may reduce missed installments, provided sufficient funds are available and account details remain accurate.
Security should remain a priority when using digital lending services. Borrowers should verify a provider’s legitimacy, review its privacy practices, and avoid sharing sensitive information through unverified websites or communications. Financial Technology is most valuable when convenience is combined with careful verification and responsible financial habits.
Strengthening Wealth Management Through Strategic Borrowing
Wealth Management involves coordinating income, savings, investments, assets, and liabilities to support long-term financial security. Borrowing decisions influence this balance because loan repayments reduce the money available for investing and saving. Reliable Loan Services can contribute to a structured financial strategy when financing supports a clear objective and the borrower understands how debt affects overall net worth.
Balancing Debt, Savings, and Investments
Borrowers should consider how loan payments affect their ability to build emergency savings, contribute to retirement accounts, and pursue suitable investments. Excessive debt can limit these opportunities, particularly when interest rates are high or income is unpredictable.
A balanced approach considers the cost of borrowing alongside expected investment returns, liquidity needs, and financial risk. Expected returns are never guaranteed, so taking expensive debt to pursue speculative investments can undermine financial stability. Maintaining an emergency reserve and prioritizing high-cost debt may be more appropriate before increasing investment contributions.
Evaluating the Long-Term Impact on Net Worth
Net worth represents the difference between total assets and total liabilities. A loan may increase liabilities immediately, but its broader financial impact depends on how borrowed funds are used, the asset acquired, repayment costs, and changes in asset value.
For instance, a mortgage may help a household acquire property while gradually reducing the outstanding principal. Nevertheless, property ownership also involves maintenance, taxes, insurance, and potential market fluctuations. Regularly reviewing assets and liabilities helps borrowers understand whether their financing decisions are supporting or weakening their long-term financial position.
Choosing a Reliable Loan Service Provider
Selecting a suitable lender requires more than comparing advertised interest rates. Borrowers should evaluate transparency, regulatory standing, customer support, repayment flexibility, data security, and the complete cost of financing. A trustworthy provider explains the terms clearly and gives customers sufficient information to make informed decisions without relying on unrealistic promises or high-pressure sales tactics.
Evaluating Transparency and Lending Terms
Before signing a loan agreement, borrowers should review the interest rate, applicable fees, repayment schedule, late-payment penalties, collateral requirements, and early repayment conditions. They should also understand whether the interest rate is fixed or variable and how that distinction may affect future payments.
A reliable lender should provide written terms and clear explanations of important conditions. Borrowers should independently verify licensing or registration with the relevant financial regulator and compare multiple offers when possible. Taking time to review documentation can help prevent misunderstandings and reduce the likelihood of expensive financial commitments.
Recognizing Responsible Lending Practices
Responsible lenders assess repayment capacity and communicate risks rather than encouraging borrowers to take on unaffordable obligations. They should explain eligibility requirements, protect customer information, and provide accessible channels for questions or complaints.
Borrowers should be cautious of guaranteed approvals that require suspicious upfront payments, unclear contracts, or pressure to disclose confidential information. Independent research and careful document review can help identify warning signs. Ultimately, a reliable loan provider should support informed decision-making while allowing borrowers to evaluate whether financing is appropriate for their financial circumstances.
Preparing for Financial Uncertainty
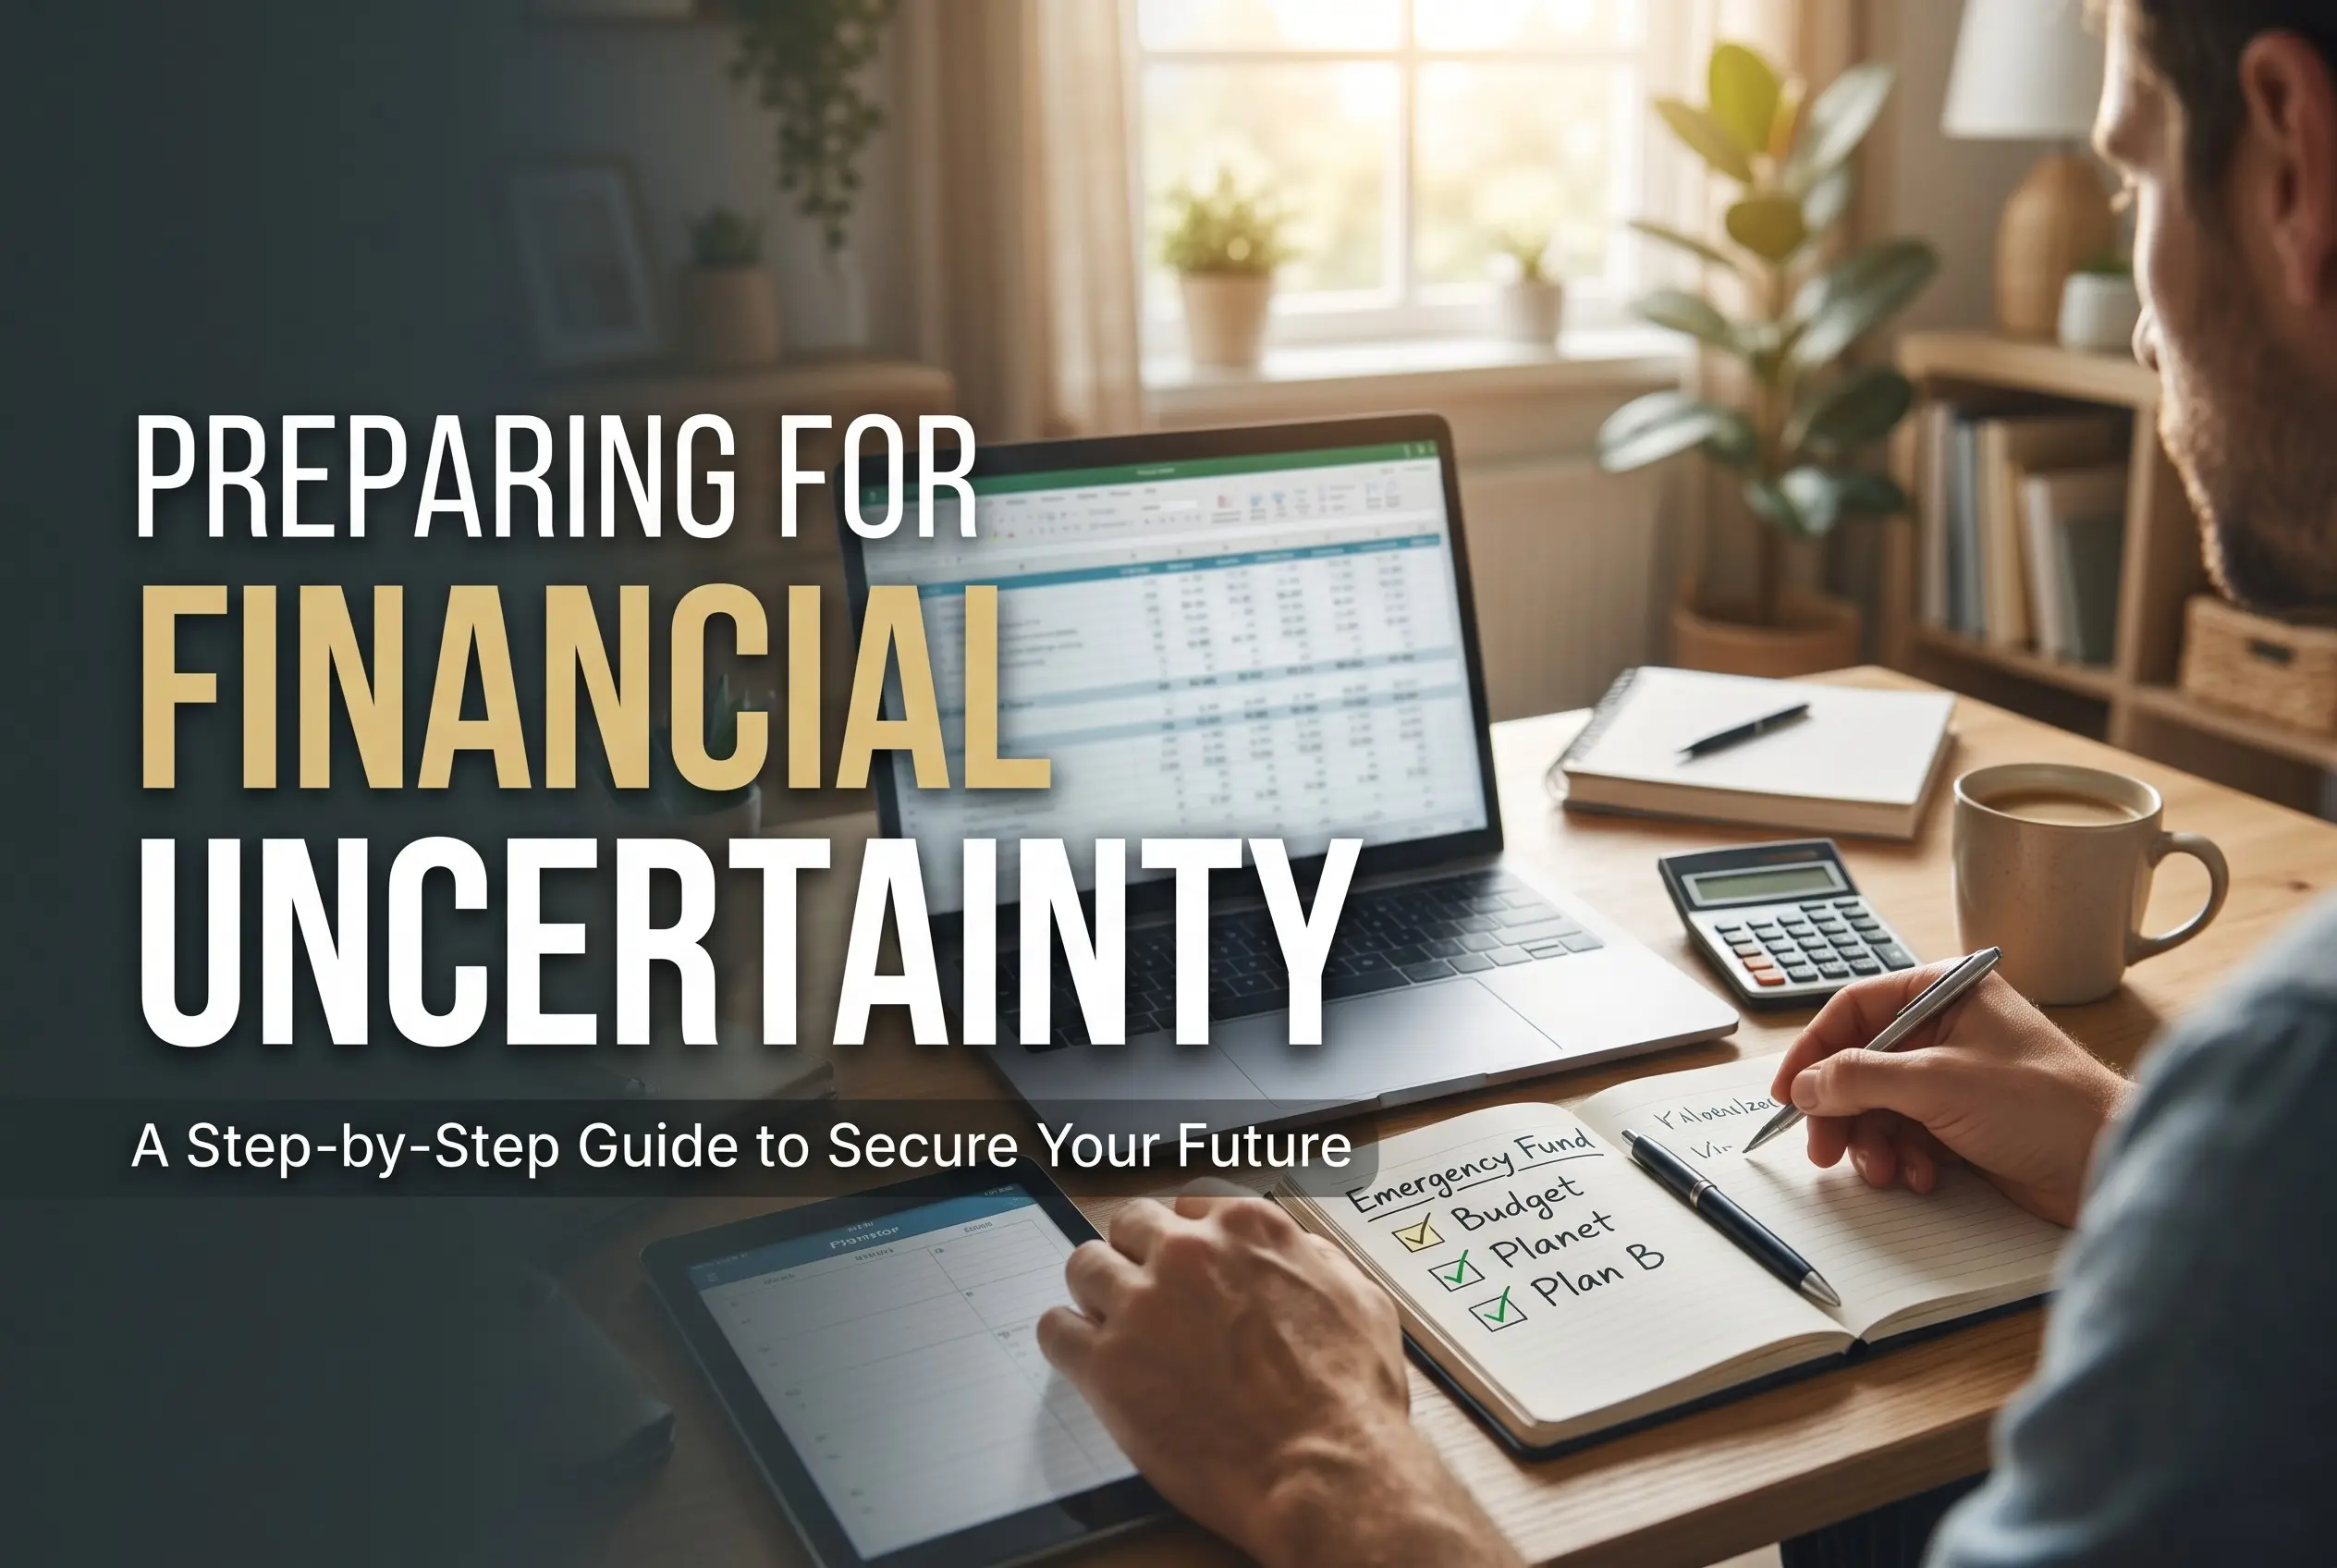
Maintaining an Emergency Fund
An emergency fund provides accessible money for unexpected expenses without requiring additional borrowing. The appropriate amount depends on income stability, household responsibilities, essential expenses, and existing financial obligations. Individuals with variable income may need a larger reserve than those with predictable earnings.
Borrowers should aim to build savings gradually while keeping required loan payments current. Separating emergency savings from everyday spending can make funds easier to monitor and protect them from unnecessary use. A financial cushion can reduce dependence on high-cost credit when unexpected expenses arise.
Reviewing Financial Plans Regularly
Financial plans should be reviewed whenever income, expenses, interest rates, family responsibilities, or major goals change. Periodic reviews help borrowers identify whether their repayment strategy remains affordable and whether their current financing still supports their priorities.
If repayment difficulties appear likely, borrowers should contact their lender early to discuss available options. Depending on the agreement and applicable regulations, possible solutions may include revised payment arrangements or restructuring. Any change should be evaluated carefully because extending a repayment period may increase the total interest paid.
Conclusion
Reliable Loan Services can play a valuable role in long-term financial planning when borrowing decisions are based on affordability, transparency, and clearly defined goals. Suitable financing may help individuals purchase property, invest in education, or support business development while maintaining an organized approach to cash flow and debt repayment.
Combining responsible borrowing with effective Tax Planning, secure Financial Technology, and balanced Wealth Management creates a stronger foundation for financial stability. Borrowers should compare lenders, understand contractual obligations, maintain emergency savings, and review their plans regularly. Ultimately, the purpose of reliable financing is not simply to obtain money but to support meaningful financial goals without sacrificing future security.
Frequently Asked Questions
1. What Are Loan Services?
Loan Services help individuals and businesses access financing for personal, property-related, educational, or commercial needs. Depending on the provider, services may include application processing, repayment management, loan administration, and information about borrowing terms.
2. How Do Reliable Loan Services Support Long-Term Financial Planning?
Reliable Loan Services provide transparent terms, predictable repayment schedules, and information that helps borrowers assess affordability. These features make it easier to incorporate borrowing costs into budgets, savings strategies, and long-term financial goals.
3. How Can Borrowers Choose the Right Loan?
Borrowers should compare interest rates, total repayment costs, fees, eligibility requirements, and repayment periods. They should also evaluate their income stability, existing debts, and future expenses before choosing a financing option.
4. Can Loan Services Help Improve Financial Stability?
Suitable financing can support financial stability when repayments remain affordable and borrowed money serves a clear purpose. However, excessive borrowing or missed payments can increase financial pressure and undermine long-term security.
5. What Is the Relationship Between Loan Services and Tax Planning?
Tax Planning helps borrowers understand how eligible interest expenses and other financing-related costs may affect their tax obligations. Tax treatment varies by jurisdiction and loan purpose, so borrowers should consult a qualified tax professional when necessary.
6. How Does Financial Technology Improve Loan Management?
Financial Technology provides digital tools for comparing loan options, tracking balances, reviewing payment schedules, and receiving reminders. These tools can improve convenience and organization, but borrowers should verify lender legitimacy and protect their financial information.
7. How Do Loans Affect Wealth Management?
Loans influence Wealth Management by affecting liabilities, cash flow, savings capacity, and investment opportunities. Borrowers should evaluate financing decisions in the context of their overall assets, debts, risk tolerance, and long-term financial objectives.
8. Should Borrowers Prioritize Loan Repayment or Savings?
The appropriate balance depends on interest rates, financial obligations, and emergency savings. Maintaining a basic emergency reserve while prioritizing expensive debt can be a sensible strategy, although individual circumstances may require a different approach.
9. What Should Borrowers Check Before Signing a Loan Agreement?
Borrowers should review interest rates, fees, repayment terms, late-payment penalties, collateral requirements, and early repayment conditions. They should also verify the lender’s legitimacy and ensure that the agreement is understandable and affordable.
10. How Often Should a Financial Plan Be Reviewed After Taking a Loan?
Borrowers should review their financial plans periodically and whenever a major change affects their income, expenses, or financial goals. Regular reviews help identify repayment challenges early and keep borrowing decisions aligned with long-term priorities.
AI Credit Scoring: Revolutionizing SME Banking and Digital Loans
What Is Digital Financial Literacy?
The Importance of Insurance Services in Financial Planning
What Is Financial Technology (FinTech)? Everything You Need to Know
How Reliable Loan Services Support Long-Term Financial Planning
The Importance of Insurance Services in Financial Planning
How Tax Planning Helps Individuals and Businesses Save Money
How to Create a Retirement Planning Strategy That Works